
Preface: “Everybody knows the deal is rotten. Old Black Joe’s still picking cotton for your ribbons and bows. And everybody knows.” — Leonard Cohen
Social Security – The Regressive Nature of Social Security
The following is the sixth in a series of blog posts on the subject of Social Security. The first five installments, which can be found here, here, here, here, and here:
-
-
- Reviewed the history of the Social Security program
- Explained how to claim Social Security retirement benefits
- Explained how to claim Social Security survivor and family member benefits
- Explained how Social Security benefits are taxed
- Explained how earned income is taxed to fund Social Security
-
This sixth installment will:
-
-
- Wrap up our discussion of FICA and how it is a regressive tax
-
Future posts in this series will address:
-
-
- Estimating Social Security’s returns on investment
-
Progressive vs. Regression Taxation
A flat tax is neither progressive nor regressive. Pennsylvania, for instance, at the time of this writing imposes personal income tax at a flat rate of 3.07%. A Pennsylvania resident who earned $10,000 will owe $307 in state income tax. His neighbor who earned $1,000,000 will owe $30,700.
Regular income tax imposed by the federal government has been progressive since its inception. While the rates and brackets have changed many times, the principle still holds that earners of higher incomes pay tax at higher rates.
Income tax brackets for 2026 are as follows:
| Single | Married Filing Jointly | Rate |
| $0 – $12,400 | $0 – $24,800 | 10% |
| $12,401 – $50,400 | $24,801 – $100,800 | 12% |
| $50,401 – $105,700 | $100,801 – $211,400 | 22% |
| $105,701 – $201,775 | $211,401 – $403,550 | 24% |
| $201,776 – $256,225 | $403,551 – $512,450 | 32% |
| $256,226 – $640,600 | $512,451 – $768,700 | 35% |
| $640,601 and up | $768,701 and up | 37% |
As discussed in the previous installment in this series, the FICA tax collected to fund Social Security is a separate tax collected in parallel and in addition to regular income tax. And as we will show here, FICA is a regressive tax. It is assessed at a higher rate on lower-income earners.
This is strange when you consider that the people who instituted FICA, Franklin Delano Roosevelt and his team, were political progressives. The reason they insisted on doing it this way is that they did not want Social Security to be perceived as a tax, but as an insurance product sold to the public without regard to income.
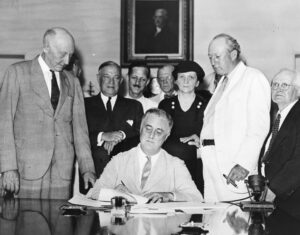
They were worried that if Social Security were seen as a tax on the rich to benefit the poor, it would fail politically. As Wilbur Cohen put it at the time: “In the United States, a program that deals only with the poor will end up being a poor program.”
So it was not their intention that it be regressive. It is regressive simply because any fixed cost represents a larger portion of a poor’s man income than of a rich man’s. In this sense, a loaf of bread is regressive, too, since its price comprises a larger percent of the poor man’s paycheck than of the rich man’s.
But regressive it is, and this becomes more of a problem both financially and politically the more expensive it gets.
The Unique Structure of Social Security
Because Social Security is not supposed to be a tax, it must be collected through a special kind of collection – FICA –that is not income tax. Because it is not supposed to be needs-based, it must be paid to rich people as well as to the poor. Because it is supposed to be insurance or some kind of investment product, the benefits paid out must scale to the premiums paid in.
None of this was done because it was ethically just or financially sound. It was for what were political marketing considerations to get the legislation passed in 1935.
In a previous post, we reviewed how Social Security retirement benefits are calculated based on lifetime earnings. The result is that high-income earners receive large benefits while low-income earners receive meager benefits.
Consider also that high-income earners tend to live longer and so receive their large benefits for more years while the low-income earners tend to receive their meager benefits for fewer years.
Consider also that high-income earners are more likely to be married and so are more likely to have surviving spouses who can take survivor benefits. And the surviving spouses of the rich are also more likely to live longer than the surviving spouses of the poor, etc.
Regressive enough for you? It gets more regressive still…
How Regressive Does It Get?
Ironically, the most nakedly regressive aspect of FICA was put in place to stop high earners from collecting too much in Social Security retirement benefits. This is the famous “cap” on income considered for Social Security purposes. For 2026, the cap on Social Security income is $184,500.
This means that no matter how much money you earned in 2026, you cannot claim more in Social Security retirement benefits than someone who earned $184,500. And due to the unique nature of the legislation passed in 1935, it also means you do not pay more in OASDI-FICA than someone who earned $184,500.
Consider how this plays out among three employees of the same company. To keep the model simple, we are considering only the employee half of the OASDI portion of FICA:
| EXAMPLE: | Larry | Moe | Curly |
| Employee gross pay | $10,000 | $184,500 | $1,000,000 |
| Wages subject to FICA(OASDI) | $10,000 | $184,500 | $184,500 |
| Employee FICA(OASDI) | $620 | $11,439 | $11,439 |
| OASDI as % of gross pay | 6.2% | 6.2% | 1.14% |
Moe is paying more in OASDI-FICA than Larry, but only because Moe earns more. They are both paying at the same rate of 6.2%.
Curly is paying the same in OASDI-FICA as Moe. However, because his income is so much higher, this represents a far small portion of his income than Larry or Moe’s payments represent of theirs.
It’s hard to think how old FDR and his boys could have designed a more regressive system if they’d tried.


